
Credit card statements always display a "Minimum Payment Due." Paying this amount keeps your account current and protects your credit score, but minimum payment calculations are designed to extend repayment as long as possible, which maximizes the interest you pay.
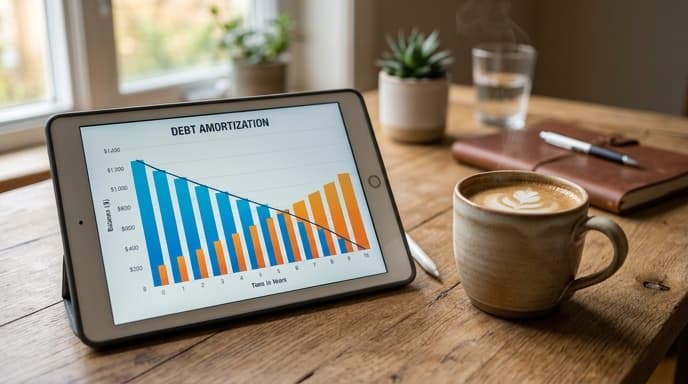
A fixed-payment credit card strategy speeds up repayment. By picking a flat dollar amount and paying it every month regardless of what the statement requests, you lower your balance faster without needing to change your monthly budget.
The Mechanics of the Minimum Payment Trap
Credit card companies usually set minimum payments based on a percentage of the balance (such as 1% to 2% plus monthly interest) or a set floor like $25 or $35, whichever is higher.
As you pay down the balance, the required minimum drops too. A minimum payment that starts at $150 might drop to $142, then $135, and eventually down to $35. Because the payment shrinks alongside the balance, only a small portion goes toward principal, stretching the debt across 15 to 25 years.
The Power of the Static Payment Floor
The fixed-payment routine keeps your monthly payment at the initial level. If your starting minimum is $200, you pay $200 every single month until the card reaches zero.
Here is how the numbers shift over time:
- Month 1: On a $6,000 balance at 22% APR, about $110 goes to interest and $90 goes to principal.
- Month 12: With a lower principal balance, monthly interest drops to roughly $85. Your $200 payment now sends $115 to principal.
- Month 24: Monthly interest drops to roughly $50. Your $200 payment sends $150 directly to principal.
Without adding any extra money to your monthly bill budget, more of your payment goes to debt reduction each month.
Worked Comparison: Minimum vs. Fixed Strategy
Take a $5,000 balance at 21% APR. Paying a standard declining minimum (1% of balance plus monthly interest) can take more than 14 years to clear and costs thousands of dollars in interest.
Setting a fixed monthly payment of $150—close to the initial minimum payment—clears the balance in about 47 months. Keeping that payment level cuts roughly a decade off the repayment period and significantly lowers your total interest.
Using an LLM to Model Your Exact Amortization Curve
You can use a language model to compare payoff timelines for different payment amounts. Do not share your real name or account numbers.
Prompt example: "I have a revolving credit card balance of $4,500 with an annual interest rate of 23.5%. Calculate a comparative repayment table comparing two options: (A) paying a sliding minimum of 1.5% principal plus monthly interest, versus (B) paying a flat, static payment of $175 every month until paid off. Show me the total months to zero and total interest paid for each option."
Frequently Asked Questions
What if my budget can only handle the minimum payment right now?
If money is tight, paying the minimum protects your credit score. Try to switch to a fixed payment as soon as you have breathing room, even by adding $10 or $15 above the minimum.
Can a fixed payment cause problems if interest rates rise?
If you have a variable APR that jumps, make sure your fixed payment is still higher than the monthly interest. If not, raise the payment to keep reducing the principal balance.
Should I direct extra cash to high-interest cards or small balances first?
Paying off the highest interest rate first saves the most money. Paying off the smallest balance first offers early wins that can help you stay motivated.
Key Takeaways
- Minimum payments drop as your balance falls, stretching out your repayment time.
- A fixed-payment approach keeps your monthly payment flat instead of letting it drop.
- A larger share of your payment goes toward principal each month as the balance declines.
- Keeping payments steady cuts years off your debt timeline without raising your budget.
- An AI model can calculate your specific interest savings and payoff timeline.
Related Reading
- Modeling Debt Avalanche vs. Snowball Payoff Using Conversational LLMs
- The Balance Transfer Fee Break-Even Math: How to Calculate True Debt Savings
- Prompt Workflows for Debt Payoff Interest Compounding Schedules