
A $900 invoice for brake work and belts is often treated as an unexpected emergency. But vehicles wear down predictably with every mile driven. Tires lose tread, oil breaks down, and suspension components wear out. These expenses only feel like surprises when drivers do not save for regular wear and tear.
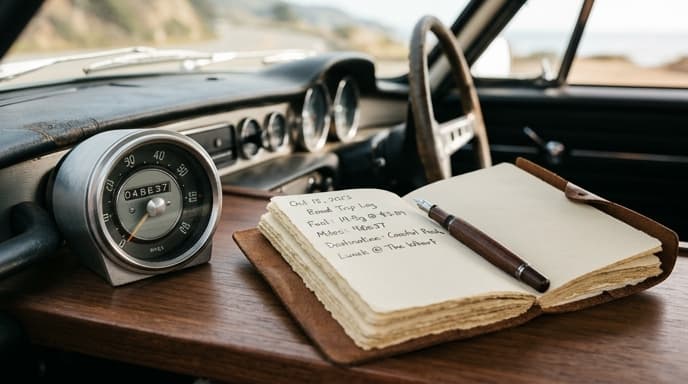
A vehicle maintenance sinking fund ties your savings directly to how much you drive instead of an arbitrary monthly guess. Drive more one month, and you save more; leave the car parked, and you set aside less.
The Flaw of Fixed Monthly Auto Allowances
Saving a flat $50 each month can leave you short when major repairs come due. Someone driving 25,000 miles a year wears through components far faster than someone driving 5,000 miles. Fixed savings treat both drivers the same, leaving high-mileage commuters unprepared when wear items need replacement.
Linking your savings rate to mileage ensures your repair fund matches the real wear on your car.
Calculating Your Vehicle Cost-Per-Mile Metric
Passenger vehicles typically require between $0.08 and $0.12 per mile for routine maintenance and tires over their lifespan. Older vehicles or European models with pricier parts often run between $0.14 and $0.18 per mile.
Use these general tiers to estimate your costs:
- Standard Tier ($0.08 to $0.10/mile): Front-wheel-drive four-cylinder sedans or small crossovers with widely available parts.
- Heavy-Wear Tier ($0.11 to $0.14/mile): Trucks, all-wheel-drive SUVs, and hybrids that need larger tires and specialized fluid services.
- High-Cost Tier ($0.15+/mile): Older luxury models, performance cars, or commercial vehicles used in tough conditions.
If you drive 1,000 miles in a month and use the $0.10 rate, move $100 into your maintenance fund.
The Monthly Odometer Audit Protocol
Managing the fund takes a quick monthly review:
- Record the starting mileage: Write down your odometer reading on the first of the month.
- Calculate miles driven: On the last day of the month, subtract your starting number from the current mileage.
- Make the transfer: Multiply your miles driven by your cost-per-mile rate and move that amount into your maintenance account.
- Use the fund strictly for maintenance: Pay for oil changes, tire replacements, inspections, and repairs directly from this balance.
Using an LLM to Build a Component Maintenance Schedule
A language model can help you map out your vehicle's upcoming maintenance milestones based on your current odometer reading.
Prompt example: "My vehicle is a 2018 compact sedan with 85,000 miles. Detail the typical manufacturer-recommended mechanical services, fluid replacements, and component wear inspections expected between 85,000 and 105,000 miles. Provide standard labor hour estimates and component categories for each service so I can budget accordingly."
Frequently Asked Questions
What should I do if my sinking fund is depleted by a repair early on?
If a repair comes up before you have saved enough, cover the rest from your general emergency fund. Then increase your per-mile savings rate slightly until you rebuild a cushion of around $1,000.
Does this fund cover gasoline and insurance?
No. Keep fuel and auto insurance in your regular monthly budget. The sinking fund is only for mechanical work, tires, and routine servicing.
Where should I keep vehicle sinking fund money?
Keep it in a high-yield savings account or a separate sub-account away from your daily spending balance so you do not spend it on everyday items.
Key Takeaways
- Car repairs are regular mileage-based operating costs, not unexpected emergencies.
- Save between $0.08 and $0.14 for every mile you drive to cover repairs.
- Check your odometer once a month to calculate your transfer amount.
- Keep maintenance money in a dedicated account so it stays intact for repairs.
- Use an AI model to list upcoming factory maintenance based on your mileage.
Related Reading
- Structuring a Zero-Sum Sinking Fund Routine for Irregular Expenses
- The $1,000 Starter Buffer: Bridging Paychecks Without Credit Cards
- How to Audit an Auto Insurance Renewal Notice Line by Line